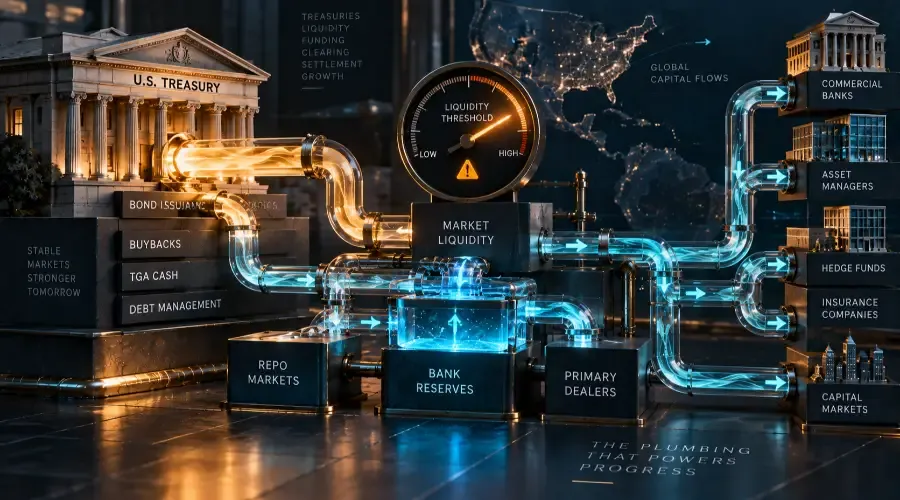
The US Treasury enlarged its bond-buyback program, repo rates and debt auctions dominated financial headlines, and passive index funds are preparing for a major portfolio reshuffle. For equity traders, most of this activity is mechanical plumbing rather than an actionable signal. Crucially, the prevailing doomer narrative–that short-term funding markets are quietly seizing up–is directly contradicted by the physical data.
Here is an institutional, plain-language breakdown of what changed in market architecture this week, what it means for your portfolio, and where the boundaries sit.
What the US Treasury Actually Did
The US Department of the Treasury operates a standing buyback program designed to repurchase older, less-liquid government bonds. This week, Treasury significantly scaled up operations at the long end of the yield curve.
For the operation scheduled on 10 September targeting the 10-to-20-year maturity bucket, the maximum purchase size was lifted to $6 billion–tripling the prior $2 billion cap. Furthermore, Treasury stated that the maximum purchase size across the six remaining scheduled buybacks of long-dated nominal debt this fiscal quarter will be equal to or greater than $4 billion.
In Treasury’s official disclosure, the explicit objective is "greater liquidity support in longer-dated nominal sectors." In everyday terms: keeping off-the-run, older bonds trading friction-free. While the published schedule remains technically tentative, history indicates that Treasury follows through; in 50 of the 52 operations conducted since the program was reintroduced in 2024, Treasury absorbed the maximum allowable amount.
The Strategic Rationale
Treasury Secretary Scott Bessent outlined the operational goal: preventing disorderly price moves and combating speculative debt-ceiling narratives in sovereign debt markets. After 30-year Treasury yields touched multi-decade highs in August amid heightened fiscal supply concerns, the buyback mechanism was deployed to absorb illiquid paper from primary dealers. By taking off-the-run bonds off dealer balance sheets, Treasury frees up institutional capacity to absorb newly auctioned on-the-run debt.
What It Is Not: Buybacks vs. Quantitative Easing
Retail market commentary frequently conflates Treasury debt operations with Federal Reserve monetary intervention. A larger Treasury bond purchase is not quantitative easing, it is not yield-curve control, and it does not represent an interest rate cut.
The table below details the structural differences between these mechanisms:
| Dimension | US Treasury Buyback Program | Federal Reserve Quantitative Easing (QE) |
|---|---|---|
| Institution | US Department of the Treasury (Debt Issuer) | Federal Reserve (Central Bank) |
| Primary Goal | Liquidity support for off-the-run, older bonds | Macro monetary easing & lower borrowing costs |
| Funding Source | Existing Treasury General Account (TGA) cash | Newly created central bank reserves |
| Balance Sheet | Does NOT expand the Fed balance sheet | Directly expands the Fed balance sheet |
| Yield Curve Impact | Smooths trading friction in specific off-the-run tenors | Lowers benchmark yields broadly via duration extraction |
| Policy Mandate | Debt management and auction participation support | Dual mandate: Price stability and maximum employment |
The operational distinction matters because true quantitative easing shifts aggregate financial conditions by creating new central bank reserves. A rate cut systematically alters the cost of capital across the real economy.
When Treasury buys back its own debt using cash balances, it behaves like a corporate borrower repurchasing illiquid obligations to maintain orderly market access. While critics correctly point out that buybacks absorb duration from the private market–marginally easing term premia–they do not expand monetary aggregates or loosen system-wide bank credit.
Evaluating the Plumbing: Stable Foundations, One Yellow Flag
If expanding buybacks stoked fears that underlying funding markets are under severe stress, short-term money market indicators tell a largely calm story, with one specific caveat:
-
Bank Reserves Remain Ample: Total bank reserves held at the Federal Reserve printed near $3.04 trillion as of 11 September, up from $2.974 trillion in mid-August. This fits the Fed’s framework for "ample liquidity," preventing cash scrambles in overnight interbank markets.
-
SOFR Is Anchored: The Secured Overnight Financing Rate (SOFR)–the benchmark rate for borrowing cash overnight against Treasury collateral–eased to 3.62% on 10 September (down from 3.64%), while the effective fed funds rate held steady at 3.63%. When secured funding rates remain calm, overnight liquidity is circulating efficiently.
-
Sovereign Debt Auctions Saw Healthy Demand: The 3-year Treasury note auction placed $58.0 billion at a bid-to-cover ratio of 2.72, while the 10-year note reopening placed $39.0 billion at 2.71. Bid-to-cover ratios above 2.7 reflect dependable, ordinary dealer and end-investor sponsorship.
-
The TGA Cash Drain Injected Liquidity: The Treasury General Account fell $36.3 billion on 9 September and another $25.6 billion on 10 September, bringing the cash buffer to $818 billion. A declining TGA releases liquidity into commercial bank reserves, temporarily suppressing repo rate pressure.
The Lone Yellow Flag: Standing Repo Facility (SRF) Take-Up
While headline liquidity metrics look serene, money markets were not completely frictionless. Take-up at the Fed’s Standing Repo Facility (SRF) surged to nearly $26 billion heading into quarter-end–marking the second-highest level since 2020.
The SRF is an emergency liquidity backstop where eligible counterparties can exchange Treasuries for overnight cash at a designated premium. Elevated borrowing at the SRF demonstrates that certain primary dealers experienced localized balance-sheet constraints, choosing to tap the Fed's backstop rather than pay up in private repo markets.
This is not a systemic breakdown akin to September 2019, but it signals that dealer absorption capacity is being tested as heavy Treasury issuance collides with balance-sheet constraints.
The Actionable Calendar Event: September Index Reconstitution
Unlike macro plumbing, index reconstitutions carry concrete dates, defined tickers, and mandatory institutional capital flows. Both S&P Dow Jones Indices and FTSE Russell are implementing their quarterly rebalancing schedules simultaneously:
| Index Event | Effective Timing | Key Changes & Documented Tickers | What It Means for Traders |
|---|---|---|---|
| S&P 500 Quarterly Rebalance | Prior to the open on Monday, 21 September | Additions: Bloom Energy (BE), Everpure (P), Illumina (ILMN)Deletions: Molson Coors (TAP), The Trade Desk (TTD), Builders FirstSource (BLDR) |
Passive index funds must mechanically rebalance. Volume spikes sharply at the Friday closing auction. |
| S&P 100 Large-Cap Changes | Prior to the open on Monday, 21 September | Additions: Dell (DELL), Palo Alto Networks (PANW), Arista (ANET), SanDisk (SNDK)Deletions: Honeywell Aerospace (HONA), Nike (NKE), Simon Property (SPG), Colgate-Palmolive (CL) |
Concentrated mega-cap reweighting. Changes represent liquidity events, not fundamental rating shifts. |
| FTSE Russell USA Review | Effective Monday, 21 September | Broader benchmark reconstitution across Russell 1000/2000 indices (~$12.2T tracking). | Substantial multi-billion dollar turnover in closing crosses; temporary spread widening. |
Trillions of institutional dollars track these benchmarks via passive index funds. When a company is added or dropped, tracking funds must execute corresponding buy or sell orders to eliminate tracking error, concentrating massive order flow into the closing cross on the final trading session before the effective date (Friday, 18 September).
This produces notable spikes in liquidity and short-term volatility. However, equity investors must separate structural business health from mechanical index inclusion. These portfolio shifts reflect passive mandate compliance, not an analytical upgrade or downgrade of corporate fundamentals.
Thesis Tracking: What Signals to Monitor Next
To separate ongoing operational noise from legitimate systemic stress, track these measurable market milestones over the coming fortnight:
| Systemic Thesis Strengthens (Stress Emerges) If... | Baseline Plumbing Holds (Calm Persists) If... |
|---|---|
| SOFR spreads persistently trade above the Interest on Reserve Balances (IORB). | SOFR remains anchored below or in-line with IORB. |
| Daily Standing Repo Facility (SRF) borrowing consistently surpasses the $25B–$30B threshold. | SRF utilization normalizes back toward negligible levels post quarter-end. |
| Treasury General Account (TGA) rebuilds aggressively, draining bank reserves below $2.9T. | Bank reserves stay comfortably above the $3.0T ample liquidity benchmark. |
| Primary dealer Treasury auction bid-to-cover ratios slip sharply below 2.3. | Bid-to-cover ratios maintain healthy demand patterns between 2.5 and 2.8. |
Bottom Line
Financial market plumbing captured the headlines this week, but high activity must not be mistaken for systemic instability.
The US Treasury’s decision to enlarge long-dated buybacks is debt management–not a hidden Federal Reserve bailout, not quantitative easing, and not an emergency pivot in interest rate policy. Funding benchmarks like SOFR remain calm, bank reserves sit above $3.0 trillion, and primary auctions are clearing smoothly, even as isolated SRF usage highlights localized dealer inventory limits.
For stock traders, the single event carrying actual mechanical weight is the 21 September index reconstitution. Track the closing auctions for temporary liquidity dislocations in newly added and deleted tickers, but leave the catastrophic repo headlines on the shelf.
Source Verification & Institutional Data Notes
-
US Department of the Treasury: Operational Tentative Buyback Schedule & Parameter Announcements (9 September 2026).
-
Federal Reserve Bank of New York: Reference Rates (SOFR at 3.62%, 10 September 2026) and Standing Repo Facility Transaction Operations.
-
Federal Reserve Board of Governors: H.4.1 Release (Factors Affecting Reserve Balances, $3.04T as of 11 September 2026).
-
US Department of the Treasury: Daily Treasury Statement (TGA balances and daily outlays, 9–10 September 2026).
-
S&P Dow Jones Indices: Press Release on Quarterly S&P 500 & S&P 100 Rebalancing (Published 4 September 2026; effective prior to the open on 21 September 2026).
-
FTSE Russell: Q3 Comprehensive US Equity Benchmark Review Schedule (Effective 21 September 2026).
This analysis is published strictly for educational and informational purposes and does not constitute investment, financial, or legal advice. Securities mentioned illustrate documented regulatory and financial reporting mechanisms from public filings.